
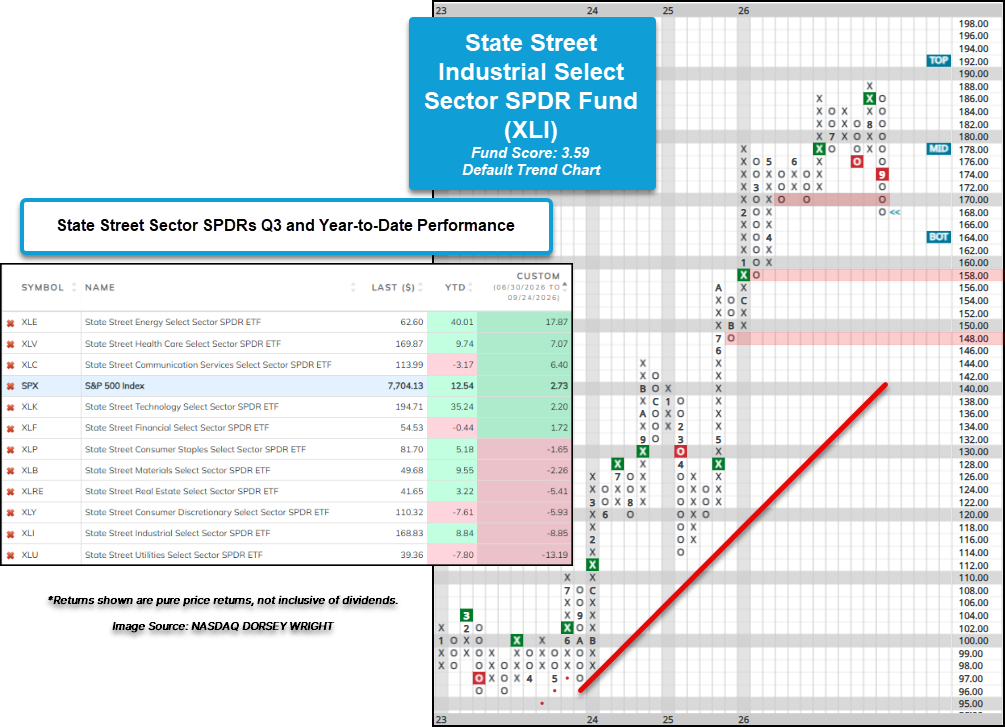
As Q3 nears a close, maybe surprisingly one of the worst performing sectors over the last few months has been industrials. Downside trading has brought the market relative strength chart into a column of Os, highlighting near-term underperformance by the fund relative to the broader market.
As Q3 nears a close, maybe surprisingly one of the worst performing sectors over the last few months has been industrials. The State Street Industrial Select Sector SDPR Fund (XLI) has fallen more than 8% during the third quarter (through 9/24), second worst only to utilities. This figure marks the worst quarter since June 2022 and worst Q3 performance since 2011. Much of the downside within the sector has come since mid-August, following a rally to all-time chart highs in the upper $180s. The trend chart returned to a sell signal at $174 to kick off September before falling into the upper $160s, taking out support that had been in place since May of this year. Downside trading has brought the market relative strength chart into a column of Os, highlighting near-term underperformance by the fund relative to the broader market.
With the broader sector seeing downside, participation has seen a shift with many of the technical indicators for the broader sector seeing recent drops to their lowest levels since March or April of this year. When XLI was marking a new all-time chart high on the chart, it did so with roughly half (50%) of the stocks within the broader sector maintaining a point and figure buy signal. Trading since has brought the bullish percent for the sector (^BPECINDUST) down to the mid-30s to mark its lowest level since April this year, suggesting that just roughly 1/3rd of the stocks maintain a buy signal as of close on 9/24. Along with a decline in stocks maintaining buy signals, the long-term positive trend indicator for the broader sector (^PTECINDUST) has similarly fallen from 50% on the chart down to the upper 30% range. Bear in mind, both indicators mentioned have yet to reach oversold territory like the short-term 10-week, which has dropped below 30%. All still reside above extreme oversold territory last witnessed in early 2025, but the negative performance and participation deterioration has impacted the long-term relative strength picture for the sector as well.

On the Asset Class Group Scores page - which is used to measure intermediate-term relative strength and trending characteristic of asset groups consisting of ETFs and mutual funds – the industrials group has fallen to just above the all-important 3 score threshold (utilizing the fund score system range from 0 to 6). This comes after the group had scored above 4 for most of the last 12 months. Although the Asset Class Group Scores page places industrials on the cusp of maintaining a positive technical picture in the intermediate-term, the long-term relative strength sector rankings within the Dynamic Asset Level Investing (DALI) tool have seen a notable change in strength for industrials.

Following Monday’s (9/21) trading, the industrials sector fell to 6th (out of 11) within the DALI sector rankings, marking the first time since mid-2022 that the sector fell into the bottom half of overall rankings. Although, technology and communication services still reside within the top half of the DALI sector rankings, industrial’s move out of the top five gives the DALI sector rankings a more risk-off tilt with the likes of healthcare, energy, and financials among the upper echelon.

Given industrials fall into the bottom half of the DALI sector rankings, the tables below examine the forward performance of the State Street Industrial Select Sector SPDR Fund (XLI) whenever the sector moves above and below the bottom half of the rankings. Given the turning point the ranking serves, forward performance in the short-term tends to be mixed to negative. This highlights that the mid-point of the DALI sector rankings have historically served as either the beginning of long-term deterioration or a near-term floor, with the latter occurring more often in recent years when examining the sector ranking history back to the beginning of 2003. The main difference in forward returns is highlighted within the intermediate with 1- to 6-month forward returns, showing these periods prove to be the inflection point in whether improvement or deterioration continues. With most of the extended periods of industrials ranking low within the DALI occurring in the decade encompassing 2003 to 2013 and only one extending past a year within the past decade (2016 – present), investors may see the recent drop in the rankings as potentially a near-term floor for recent downside action. While recent history suggests that may the case, it will be important to check in roughly a month from now to see if industrials have continued lower or improved in the DALI rankings. A continued fall within the rankings may be signs of additional downside to come in 3 to 6 months, while improvement in the rankings is a sign the sector has found its footing.

