Major indices were able to survive September relatively unscathed, but things were not as calm underneath the surface.
Markets were able to survive September relatively unscathed, despite it historically being the weakest months for markets. The S&P 500 was down around half a percent, but things were not as calm underneath the surface, with much of those gains being driven by the market’s largest companies. The Nasdaq-100 (NDX) rose 3.2% for the month, with the index also returning to all-time highs. Meanwhile, markets were dragged lower by the average stock, as the Equal Weight S&P 500 Index (SPXEWI) fell over 5%, highlighting the lack of broad-based upside in the market currently.

Following action this month, only a third of S&P 500 stocks trade on a buy signal, as measured by NDW's (^BPSPX) indicator. More stocks participating in upside is constructive for markets, as it’s easier for indices to rise when more stocks are gaining ground. Conversely, fewer stocks moving higher (like we’ve recently seen) makes it harder for the market to rise, a potential cause for concern. That said, the market can always move higher at the hands of just a few stocks, as we saw in 2023. Overall, domestic equities continue to demonstrate relative strength, ranking behind only international equities, keeping it firmly as a favored area for the time being.
Within domestic equities, the technology sector put together another standout month. Representative XLK gained 5% during September, which was easily the most of any major sector. Healthcare and communications round out the top three sectors by relative strength. Meanwhile, industrial has lost some steam, with proxy XLI more than 10% away from previous highs, leaving the sector as more of a neutral area after its deterioration.
Looking ahead, investors are entering one of the most interesting parts of the year. October has seen notable bouts of volatility. Some of the more notorious market meltdowns have occurred during the month, including 1978 (-9%), 1987 (-22%), and 2008 (-17%). However, the month is positive more often than not and is sometimes referred to as the "bear killer," as its end ushers in the beginning of the seasonally strong six months of the year. In fact, the S&P 500 (SPX) has had more double-digit gains in October than it has double-digit losses since 1950.
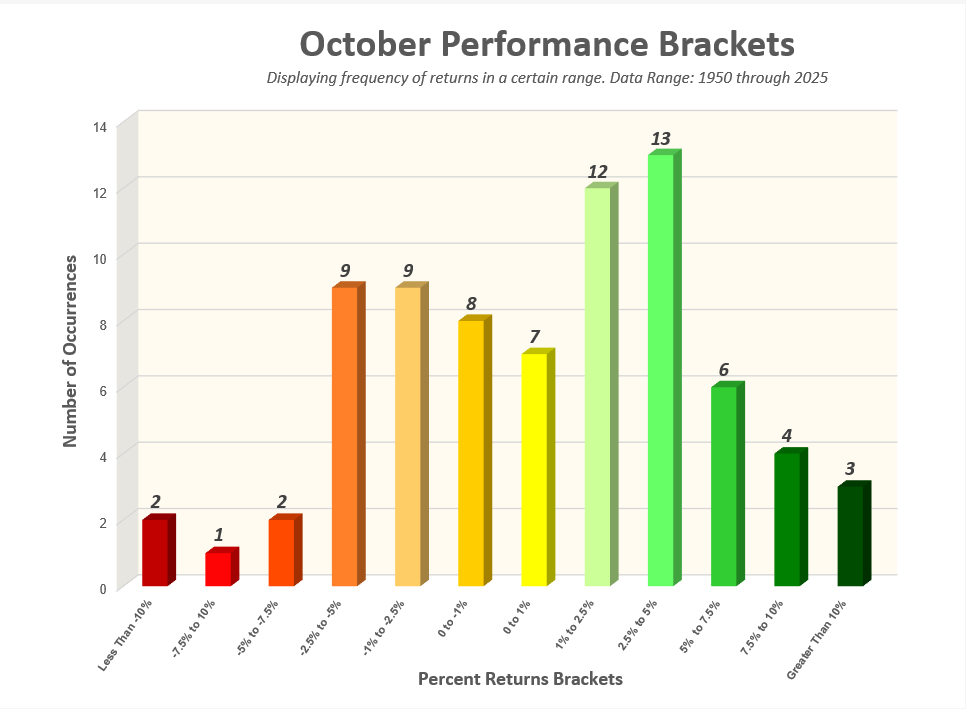
Additionally, October marks the start of the fourth quarter, which has historically been the best quarter for markets. Additionally, the fourth quarter of midterm election years has been even more positive than usual. The S&P 500 has been positive in 83% midterm fourth quarters since 1928, which is far above the average of two thirds for all quarters, serving as another sign of optimism as we close out 2026.

