The end of summer is upon us, and while most kids and college students returned to school, markets were busy returning to all-time highs.
The end of summer is upon us, and while most kids and college students returned to school, markets were busy returning to all-time highs in August. The S&P 500 gained 2.62%, setting new highs around 7,800 before ending the month slightly below that. Meanwhile, international equities also continued to push higher as well. Foreign equity representative ACWX rose 2.86% to set all-time highs, and both developed and emerging market stocks were solid contributors with positive returns. Back on the domestic front, growth areas of the market reversed some of their downside from July, with the Nasdaq Composite gaining 3.83%, which was among the best returns of any major index.

After a bloodbath for technology stocks in July, the sector saw a strong rebound as earnings for the group continued to grow. The technology select sector SDPR fund XLK rose 6.4%—the 2nd best of any major sector—following its 7.7% decline in July. Software companies were the major standout among tech areas, with the iShares North American Tech-Software ETF (IGV) rising another 16.3% this month, allowing it to recover all of its previous losses this year.
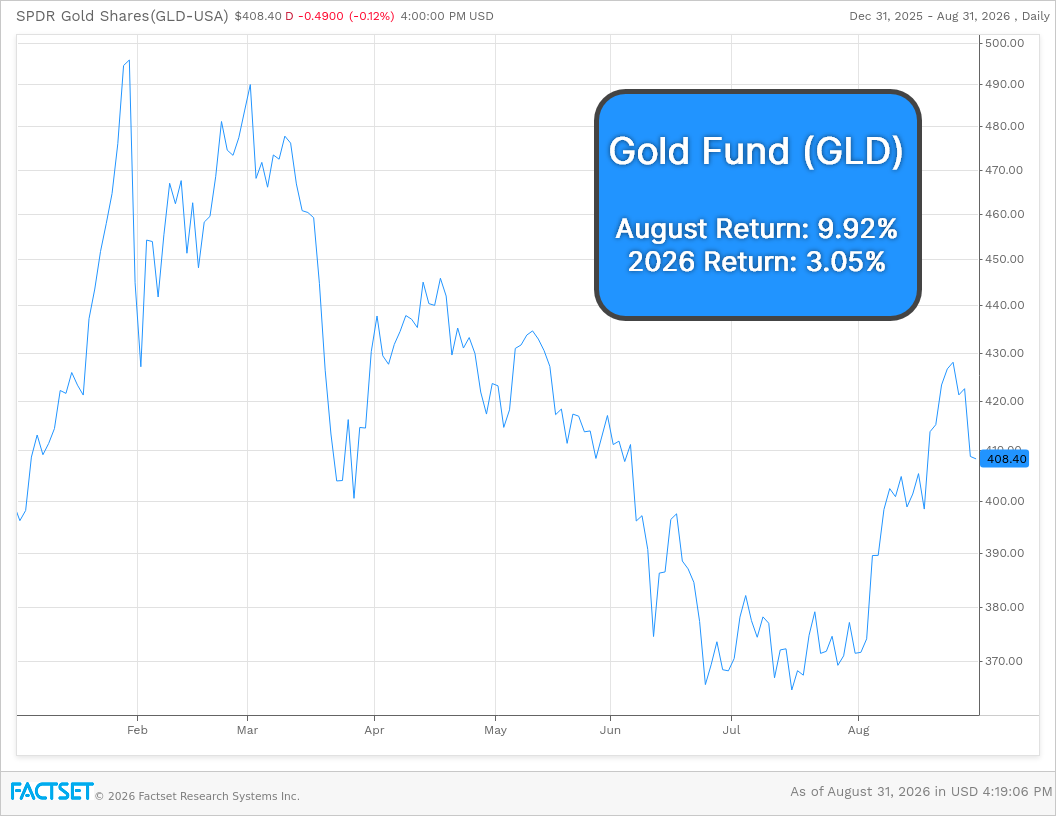
It wasn’t just stocks that rose last month, as commodities put together one of their strongest months since the beginning of the year. Crude oil has moved significantly in each of the last several months due to conflict in the Middle East, but it broke that trend this month, rising a mere 1% as it consolidated. However, we saw precious metals rebound sharply after trending lower in recent months. Gold fund GLD climbed around 10% while silver fund SLV performed even better with a 15% gain. That said, the long-term strength of commodities continues to lag behind domestic and international equities.
Looking ahead, September has historically been one of the weakest months for financial markets. It is the only month that has a negative median return, and the S&P 500 averages a 1.1% decline during the month since 1958. The S&P 500 fell in four of the last six Septembers, averaging a 2.9% monthly decline over that span. Not every September has been negative, but there is slightly more potential for turbulence over the next month if historical averages have anything to say about it.

Similarly, the third quarter of midterm election years has also been one of the weakest in the election cycle, as the S&P 500 has averaged a decline of 0.8% since 1930, with policy uncertainty serving as a drag. However, when the market finds more stability with less uncertainty, it has historically been a catalyst for further upside. During the fourth quarter of midterm years, the S&P 500 has been positive 83% of the time while averaging a 5.6% return, which bodes well for the tail end of 2026.

