If it feels like the market has been on a historic rally the last two months, that’s because it has been.
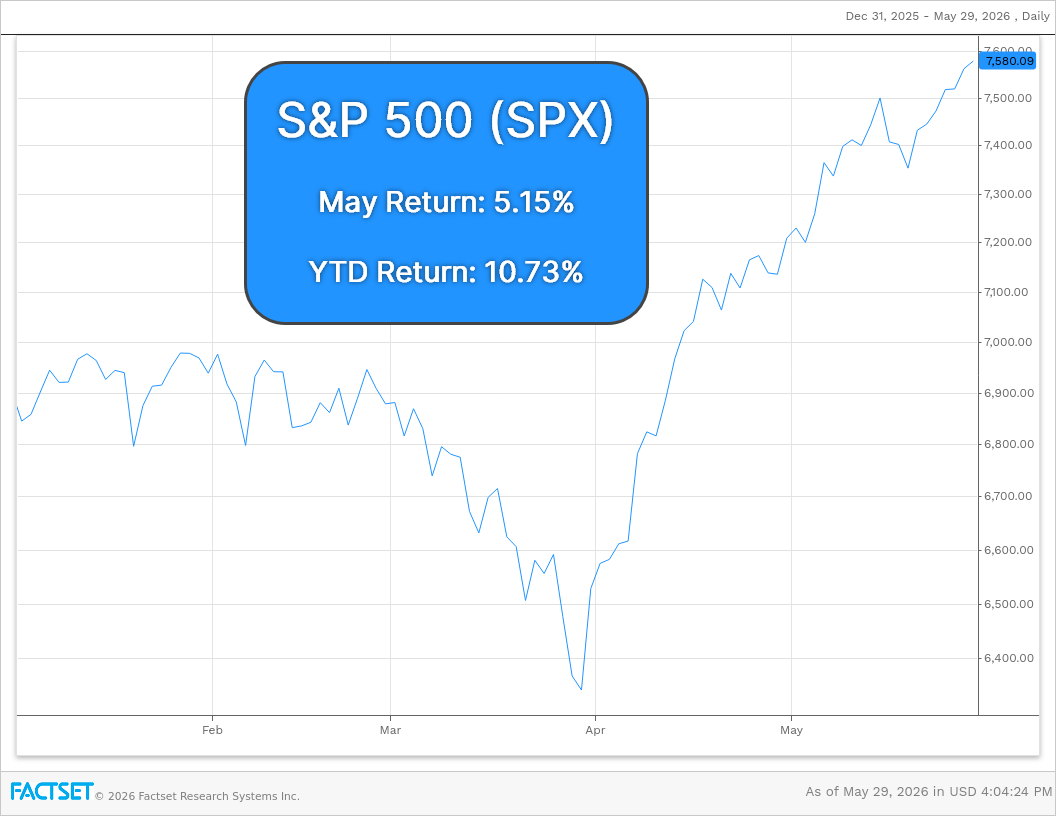
If it feels like the market has been on a historic rally the last two months, that’s because it has been. The S&P 500 has risen in each of the last nine weeks, which is only the second time that’s occurred in the last 20 years. Meanwhile, the market has gained 16% since the end of March, which is the best two-month period for the index since it rallied off the Covid-19 lows in 2020. No matter how you slice it, the market has been extraordinary of late.
Technology continues to be the dominant force in the market, with fund XLK rising another 20%, bringing its return over the last two months to an eye-opening 43.5%. The sector continues to benefit from the AI buildout, but this past month saw upside from more than just the usual semiconductor names. Software and cybersecurity names have rebounded notably after selling off earlier this year, allowing the broader technology sector to overtake energy as the top sector in our rankings.

International equities also remain a point of strength within the market. Foreign stock fund ACWX rose another 4%, bringing its year-to-date gain above 14%. Meanwhile, emerging markets have been an area of strength within the broader international space. Emerging market fund EEM rose another 7.3% in May, helped in part by strength in many of its technology names. South Korea has been the best performing emerging market this year, as proxy FLKR has doubled since the start of the year, with memory companies like Samsung and SK Hynix leading the way higher.
Kevin Warsh stepped in as the new Chairman of the Federal Reserve, and he comes in facing an uphill battle against inflation. PCE inflation was released at the end of the month, coming in at 3.8%, its highest level since 2023. Even excluding food and energy, PCE inflation—viewed as the Federal Reserve’s preferred measure—came in at 3.3%, also its highest level since 2023. While both numbers were roughly in line with expectations, the persistence in inflation has left investors expecting rate increases from the Fed over the next year, whereas several more cuts this year were expected as recently as three months ago. A rise in interest rates could eventually be a headwind for bonds, equities, and the economy, but weakness within stocks has yet to materialize whatsoever.
Despite the flurry of headlines and economic developments this year, leadership within equities has been extremely consistent, allowing momentum and trend following strategies to shine. Momentum fund MTUM has outperformed the S&P 500 by over 15% since the start of the year, marking the widest spread in favor of high-momentum stocks since 2017. Areas of leadership like technology continue to hold firm, which is an optimistic sign for momentum investing as we look ahead to the rest of the year.

