
With the start of November, we have also officially moved into the “seasonally strong” half of the year, which lasts from November through April.
With the start of November, we have also officially moved into the “seasonally strong” half of the year, which lasts from November through April. We are all familiar with the saying "sell in May and go away," which proposes that portfolio growth would do about as well if all holdings were sold as they would be if invested in the market from May through October. Typically, conjecture doesn’t mature into an adage without basis and market seasonality is just such an example as it has shown an impressive trend in terms of magnitude, consistency, and longevity. We’ve discussed seasonality many times over the years and as we switch between seasonally biased periods, we wanted to revisit the subject today.
The end of trading on Friday, October 30 brought the end of the seasonally weak period, which began with the close of the market on Thursday, April 30, 2025. Over this period, the Dow Jones Industrial Average (.DJIA) returned 4.27%, marking the third consecutive year of positive gains during the seasonally weak period
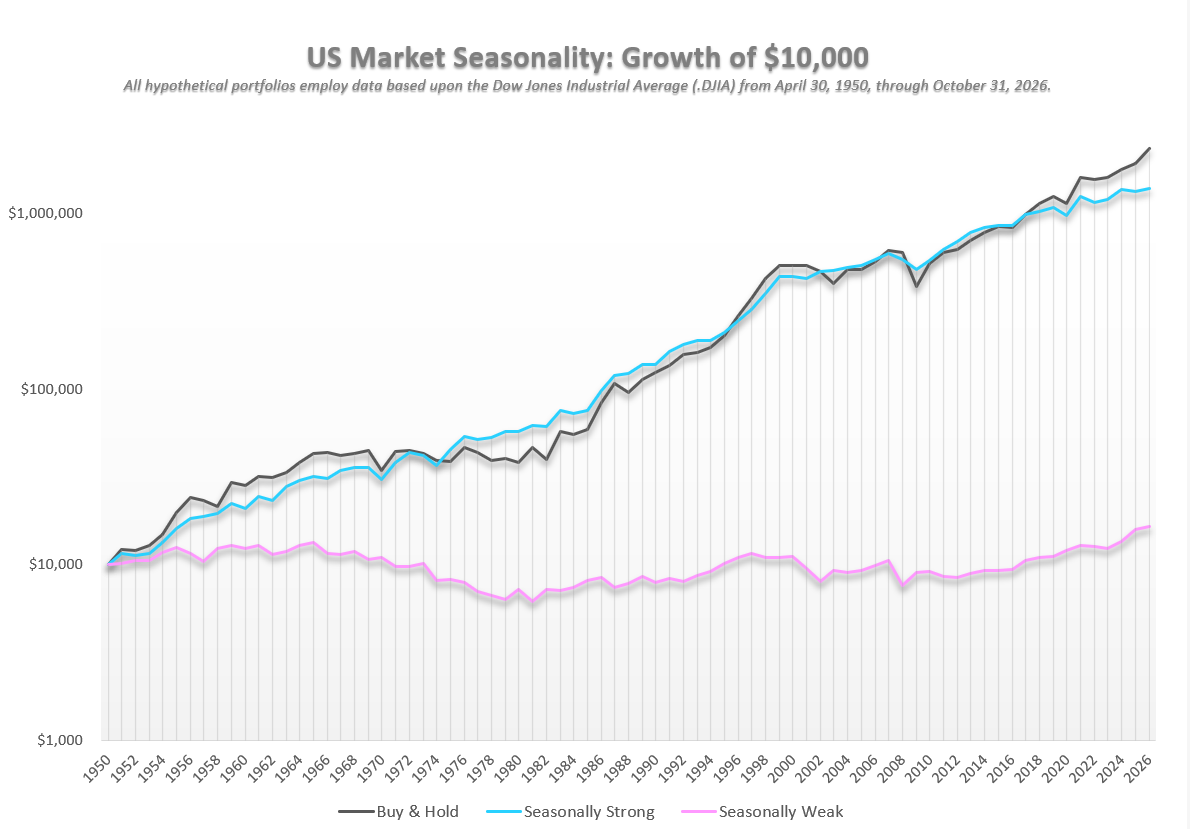
Years ago, we began using the Stock Trader's Almanac, a reference tool published by Yale Hirsch that has been a fantastic source of information on the stock market ever since. In fact, we always order several copies for the office each year (if you would like a copy, you can visit www.stocktradersalmanac.com). The premise of the "Market Seasonality" study is that historically speaking, the market performs far better during the November to May period than it does from May to November. On its own, that isn't a particularly profound statement. However, when we examine the magnitude of this effect over the years, its significance becomes clear. Consider this: if you had invested $10,000 in the Dow Jones on April 30 and sold it on October 31 each year since 1950, your cumulative return would be only about $16,598. Meanwhile, the same $10,000, invested only during the seasonally strong six months of the year, would now be worth a little under $1.4 million. Put another way, almost all the growth of the Dow since 1950 has effectively occurred during the "good" six months of the year.

In the graph below, we have reproduced the US Market Seasonality strategy that was first published in the Stock Trader's Almanac beginning in 1950 based upon the Dow Jones Industrial Average. The pink line reflects the seasonally weak period, while the blue line shows the seasonally strong six months. You will note that a theoretical $10,000 initial investment in 1950 is barely on the positive side when invested only from May through November. On the other hand, an identical $10,000 initial investment grew to $1.4 million with an average annualized return of 6.70% if invested only from November through May each year.
Market Seasonality Notes
- Since April 28, 2000, the Dow has gained more than 362%. However, the Dow is up only about 48% if we isolate only the seasonally weak periods over the same timeframe.
- During the seasonally weak May to November periods, 29 out of the 77 years examined finished down, while there were only 17 years during which the seasonally strong period produced a negative return.
- The best strong seasonal period came in 1986 as the Dow gained over 29%, while the worst seasonally strong period came in 1970 at a 14% loss.
- The best seasonally weak period came in 1958 at a 19% gain. Only ten of the past 77 weak periods have seen double-digit gains. Meanwhile, there have been 29 double digits gains during the strong period over the same span.
- The worst seasonally weak stretch came in 2008 when the Dow lost over 27%. There have been eleven seasonally weak periods to lose more than 10%, compared to only three seasonally strong periods.
- Despite the longer-term trend, the Dow has performed better during the seasonally weak period over the last decade, with DJIA averaging a 6% return compared to 5.5% for the seasonally strong period.
- When markets are higher during the strong period, the Dow averages a return of almost 11%, highlighting a high magnitude of potential upside if stocks hold steady.
We acknowledge that this study is not a sophisticated tool for risk management, but it is interesting and does expose biases within the market. The most recent seasonally weak period was better than what history would dictate, but markets have still consolidated over the past few months. The upcoming seasonally strong period could provide a catalyst for major indices to resume their upside, especially given their long-term strength. Domestic equities recently moved back to the top of DALI’s asset class rankings while most participation indicators are starting to rebound, highlighting a favorable outlook for the group as we look ahead to the next six months.
